What is the market overview and scope of the Seamless Pipes Market?
Our analysis indicates that the Seamless Pipes Market represents a cornerstone of critical industrial infrastructure, valued at $284.14 Billion in 2026. Unlike welded alternatives, seamless tubes lack a longitudinal weld seam, allowing them to withstand significantly higher internal pressures and corrosive environments. This vital sector spans energy exploration, power generation, and heavy manufacturing, utilizing high-grade steel, nickel, and copper alloys to ensure structural integrity in extreme operational conditions.
Key market drivers, restraints, challenges, and opportunities shaping Seamless Pipes Market
Structural growth is primarily propelled by expanding upstream oil and gas exploration and stringent API standards demanding high-integrity tubular goods. However, the market faces notable restraints, including volatile raw material costs for alloy steel and stringent environmental regulations enforced by bodies like the EPA. Opportunities abound in the transition toward ultra-supercritical power plants and deepwater drilling projects, favoring manufacturers capable of producing corrosion-resistant nickel alloy configurations.
Emerging trends and growth patterns in Seamless Pipes Market
The shift toward advanced metallurgy has accelerated the adoption of cold drawn stainless steel variants to combat hydrogen embrittlement and severe stress corrosion cracking. Industry leaders are increasingly integrating digital traceability solutions and automated non-destructive testing (NDT) across manufacturing lines. These technological upgrades reduce micro-fissure defect rates, directly addressing end-user demands for certified metallurgical reliability in high-pressure subsea environments.
How did the COVID-19 pandemic impact the Seamless Pipes Market and drive the recovery trajectory?
The pandemic severely disrupted global supply chains, causing temporary shutdowns in major manufacturing hubs and a sharp contraction in hydrocarbon capital expenditures. Recovery has been robustly steered by surging global energy demands and post-pandemic infrastructure stimulus packages. Producers demonstrated resilience by optimizing continuous mandrel rolling yields and reallocating capacity toward high-margin energy transition sectors, securing a stable rebound pathway.
Competitive benchmarking and strategic dynamics in the Seamless Pipes Market
The competitive landscape is consolidated among Tier-1 multinational steelmakers such as Tenaris SA, Vallourec SA, and Nippon Steel Corporation, who leverage vertically integrated supply chains and proprietary threading technologies. Strategic positioning hinges on geographical diversification and long-term supply agreements with supermajor energy companies. Regional players like Maharashtra Seamless Ltd and Jindal Saw Ltd fiercely contest local infrastructure tenders through aggressive cost efficiencies.
Executive summary of key findings regarding the Seamless Pipes Market
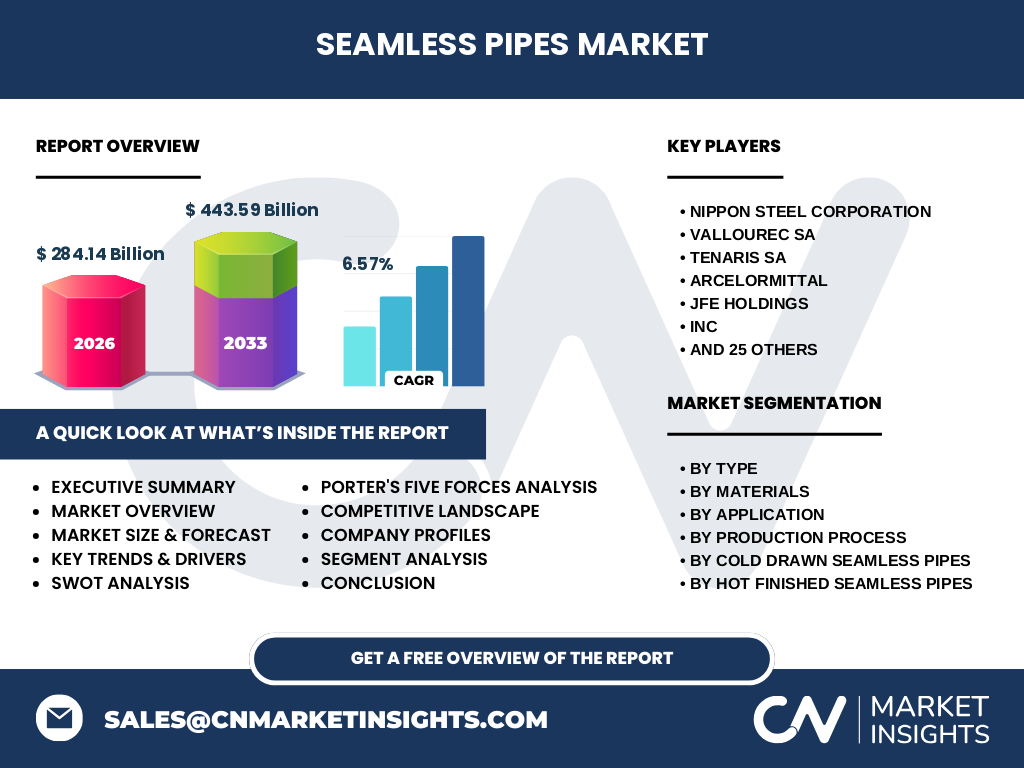
Our comprehensive research projects the Seamless Pipes Market to expand from $284.14 Billion in 2026 to $443.59 Billion by 2033, registering a robust CAGR of 6.57%. Growth is heavily anchored in rising energy demands and infrastructural modernization across developing economies. Stakeholders must prioritize technological agility in precision rolling and alloy development to capture high-value project margins.
Market forecast trajectory from 2027 to 2033
Driven by accelerating industrialization and renewable energy infrastructure build-outs, the market is poised to achieve a stellar 6.57% CAGR between 2027 and 2033. This trajectory will elevate total market valuation from $284.14 Billion to $443.59 Billion. Demand will peak in sectors requiring extreme thermal resistance, particularly advanced power generation and deep-well petroleum extraction.
Comprehensive segmentation analysis of the Seamless Pipes Market
Segmentation is categorized by type, material, application, and production process to capture precise industry dynamics.
- By Type: Covers Hot Finished and Cold Drawn Seamless Pipes.
- By Materials: Includes Steel And Alloys, Copper And Alloys, Nickel And Alloys, Magnesium Alloys, and Other Materials.
- By Application: Spans Oil And Gas, Building And Construction, Power Generation, Automotive, Aviation, and Others.
- By Production Process: Features Continuous Mandrel Rolling, Mannesmann Plug Mill Process, Cross-Roll Piercing, and Pilger Rolling.
Geographic distribution and regional performance in the Seamless Pipes Market
Regional performance varies significantly, dictated by local industrialization rates, regulatory frameworks, and upstream energy investments. The Asia-Pacific region dominates consumption due to massive urbanization and expansive manufacturing bases in China and India. Meanwhile, North America and Europe maintain steady demand focused on asset integrity management, pipeline retrofitting, and stringent emissions-compliant power generation upgrades.
In-depth regional review and localized market constraints
North American growth is underpinned by rigorous regulatory compliance mandated by agencies like OSHA and PHMSA, necessitating high-specification alloy replacements. In contrast, Asia-Pacific dynamics are shaped by rapid capacity expansions from market participants like Baosteel Trading Co. and Ansteel Group. European markets face stringent environmental taxation, pushing producers toward energy-efficient pilger rolling and scrap-metal recycling initiatives.
Company profiles and strategic positioning of leading industry participants
Industry titans like Tenaris SA and Vallourec SA focus heavily on proprietary premium connections and digital rig-site services. ArcelorMittal and Nippon Steel Corporation leverage vast metallurgical R&D networks to supply advanced automotive and aviation-grade tubes. Regional specialists such as Tubos Reunidos and Maharashtra Seamless Ltd capture market share through rapid delivery cycles and localized customer engineering support.
Porter's Five Forces analysis of the Seamless Pipes Market
The industry exhibits moderate-to-high barriers to entry due to massive capital expenditure requirements for continuous mandrel rolling mills and strict quality certifications. Supplier power remains balanced, as raw material inputs like ferroalloys are subject to global commodity pricing fluctuations. Buyer power is tempered by the critical nature of the end-use applications, where product failure is not an option, prioritizing certified quality over cost minimization.
SWOT analysis highlighting strategic strengths and market threats
Strengths lie in superior metallurgical durability and proprietary high-pressure connection designs. Weaknesses include high energy consumption during thermal piercing and sensitivity to raw material price volatility. Opportunities center on hydrogen transportation infrastructure and geothermal energy expansion. Threats involve intensifying trade tariffs, anti-dumping duties, and substitution threats from advanced composite piping materials.
Value chain analysis from raw materials to end-user deployment
The value chain initiates with the extraction and processing of iron ore, nickel, and alloy additives, followed by electric arc furnace steelmaking. Primary manufacturers utilize complex thermal processes like cross-roll piercing and mandrel rolling to form seamless hollows. Finished tubes undergo rigorous nondestructive testing (NDT) before distribution via specialized logistics hubs to end-users in energy, automotive, and aviation sectors.
Investment insights and high-potential areas for capital allocation
Investors should direct capital toward manufacturing facilities specializing in nickel-alloy and stainless-steel cold drawn pipes, which command superior profit margins. High-potential opportunities exist in digital transformation initiatives, such as AI-driven surface defect detection and predictive maintenance systems within rolling mills. Companies integrating low-carbon steelmaking technologies will also outperform regulatory scrutiny.
Conclusion and key takeaways for executive decision-makers
The Seamless Pipes Market offers robust expansion prospects, projected to reach $443.59 Billion by 2033. Success requires navigating stringent regulatory landscapes while capitalizing on high-growth segments like advanced energy generation and specialized alloy applications. Strategic alignment with technological innovators will separate market leaders from legacy laggards.
Research methodology and data triangulation framework
Our baseline estimates are rigorously triangulated by synthesizing primary stakeholder interviews with c-suite executives, global trade registry data, and secondary macroeconomic indicators. We cross-reference production volume statistics from industry associations with financial filings of key players like Jindal Saw Ltd and Salzgitter AG. This multi-tiered approach ensures high statistical fidelity and reliable market sizing.
Scope of the report and analytical limitations
This report encompasses a comprehensive global evaluation of the Seamless Pipes Market across all primary material categories, production processes, and application verticals from 2026 to 2033. Limitations include unforeseen geopolitical trade embargoes, sudden currency fluctuations, and localized supply chain bottlenecks that may momentarily alter regional growth velocities.
Recent developments, strategic partnerships, and product launches
Recent industry momentum is defined by strategic investments in decarbonized manufacturing processes and capacity expansions targeting renewable energy sectors. Major participants have launched advanced corrosion-resistant alloy tubes designed specifically for hydrogen fuel transport and carbon capture utilization and storage (CCUS) facilities, future-proofing their product portfolios against evolving energy demands.